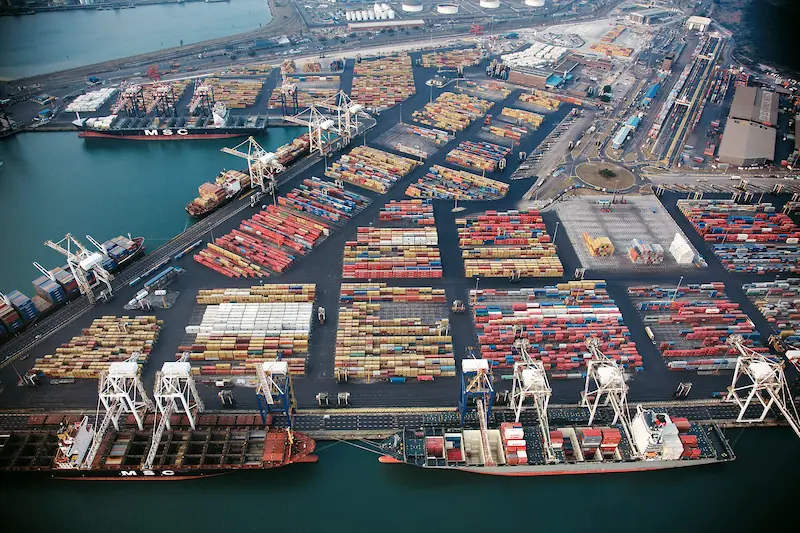
For three decades, globalization was framed as an irreversible process driven by market efficiency and interdependence. Today, that narrative has fractured. Governments across North America, Europe, and parts of Asia increasingly speak not of free trade but of “de-risking.” The term suggests prudence rather than rupture—strategic diversification rather than wholesale decoupling. Yet its implications are profound. Is de-risking merely a tactical adjustment within globalization, or does it represent a structural redefinition of the global economic order?
The answer matters because de-risking now informs trade policy, industrial strategy, and national security doctrine. It shapes semiconductor subsidies, supply-chain restructuring, export controls, and foreign investment screening. Unlike the rhetoric of outright deglobalization, de-risking claims to preserve openness while reducing vulnerability. Whether that balance is sustainable remains contested.
De-Risking and the Future of Globalization
De-risking emerged prominently in transatlantic policy discourse amid escalating strategic competition with China. Rather than advocating full economic decoupling, policymakers argue for limiting exposure in critical sectors—advanced chips, rare earths, telecommunications infrastructure, and green technologies.
The concept rests on a risk-based logic. Interdependence is no longer seen as inherently stabilizing. Instead, asymmetrical dependencies are viewed as potential leverage points in geopolitical conflict. The policy objective is therefore selective insulation: diversify suppliers, reshore key industries, and build “trusted” trade networks among allies.
This marks a departure from the classical liberal assumption that efficiency maximization should dominate trade decisions. Economic policy is increasingly subordinated to strategic resilience. The shift does not end cross-border exchange; global trade volumes remain substantial. But it introduces a new hierarchy of values in which security considerations constrain market openness.
Industrial Policy Returns
One tangible manifestation of de-risking is the revival of industrial policy. Governments are deploying subsidies, tax incentives, and public–private partnerships to secure domestic capacity in critical sectors. Semiconductor manufacturing, battery production, and clean energy technologies have become focal points.
Industrial policy had long been viewed with skepticism in advanced economies, associated with inefficiency or protectionism. De-risking reframes it as insurance. The argument is not that states can outcompete markets in all sectors, but that certain technologies are too strategically significant to leave entirely to global supply chains.
This recalibration challenges World Trade Organization norms that were designed to limit state intervention. While formal commitments remain, enforcement has weakened, and major powers increasingly justify policy exceptions on national security grounds.
The result is a more fragmented regulatory landscape. Instead of a single integrated market logic, multiple partially overlapping economic blocs may emerge—linked by trade but structured by strategic alignment.
Strategic Autonomy or Managed Interdependence?
In Europe, de-risking intersects with the concept of “strategic autonomy.” The goal is not isolation but the capacity to act independently in critical domains. Energy dependence after the invasion of Ukraine reinforced the political salience of supply-chain vulnerability. Diversification, stockpiling, and domestic capacity-building are now central policy priorities.
Yet strategic autonomy has limits. Complex technologies rely on globally distributed inputs and knowledge networks. Full self-sufficiency would be economically prohibitive and technologically regressive. De-risking therefore operates within constraints: it seeks to recalibrate interdependence, not eliminate it.
This tension defines the current phase of globalization. States aim to reduce exposure without triggering retaliatory fragmentation. The success of de-risking depends on whether selective restrictions can coexist with broader openness.
De-Risking, Development, and the Global South
A critical but underexamined dimension of de-risking concerns its impact on developing economies. If advanced democracies consolidate supply chains within “trusted” networks, countries outside these alignments may face exclusion or reduced investment flows.
For export-dependent economies, this shift could constrain growth opportunities. Conversely, some states may benefit from diversification as firms seek alternatives to concentrated production hubs. Southeast Asia and parts of Latin America have already attracted manufacturing relocations in response to geopolitical risk.
The distributive consequences of de-risking will not be uniform. They will depend on political alignment, regulatory capacity, and integration into new value chains. Globalization may become more stratified, with differentiated access rather than universal integration.
Normative and Institutional Implications
Beyond economics, de-risking raises normative questions about the relationship between markets and democracy. Advocates argue that reducing strategic dependency strengthens democratic sovereignty. Critics warn that broad security exceptions can justify protectionism and weaken multilateral governance.
If national security becomes a routine rationale for trade intervention, the rules-based order may erode further. The distinction between legitimate risk mitigation and opportunistic economic nationalism is often ambiguous. Without credible multilateral oversight, states may expand restrictions incrementally.
At the same time, the pre-2020 model of hyper-efficiency proved vulnerable to systemic shocks—pandemics, wars, and geopolitical rivalry. Resilience has become a policy imperative. The challenge lies in calibrating resilience without entrenching fragmentation.
A Durable Reconfiguration?
Is de-risking a transitional adjustment or a long-term transformation? Much depends on geopolitical trajectories. If major-power rivalry intensifies, selective decoupling could deepen into systemic bifurcation. If tensions stabilize, de-risking may settle into a pragmatic equilibrium: diversified supply chains within a still-global economy.
What seems unlikely is a simple return to pre-crisis globalization. Political tolerance for deep asymmetric dependence has diminished. Voters and policymakers alike now view economic interdependence through a strategic lens.
De-risking thus signals not the end of globalization, but its politicization. Trade and investment decisions are increasingly embedded within national security frameworks. Markets remain global, but they are no longer treated as autonomous from geopolitics.
The defining feature of this era is not closure, but conditional openness. Globalization persists—reconfigured by strategic calculation. Whether this model can sustain economic dynamism while containing geopolitical rivalry will shape the next phase of international order.